DOE Steelmaking Funding Advances as LNG Seeks Support
DOE steelmaking funding is supporting a defined $1 billion modernization plan in Ohio, while federal efforts to assist additional liquefied natural gas projects remain less specific.
American energy policy is moving beyond power plants and fuel production. The Department of Energy is increasingly using grants, loans and national-security authorities to support the industrial systems that make energy infrastructure possible.
Two developments from the week of August 21 illustrate the opportunities and limits of that approach. On August 21, DOE announced a $500 million award supporting a $1 billion modernization project at Cleveland-Cliffs’ Middletown Works steel mill in Ohio. That same day, Energy Intelligence reported that White House efforts to help new LNG projects secure federal financing and other support were “falling short so far,” according to developers and industry sources.
The contrast is significant. Federal support has produced a defined project scope and investment framework in steel. In LNG, the administration has expanded its legal and financial toolkit, but developers still face permitting, regulatory, financing and long-term commercial requirements
A $500 Million Steel Award With a Revised Mission
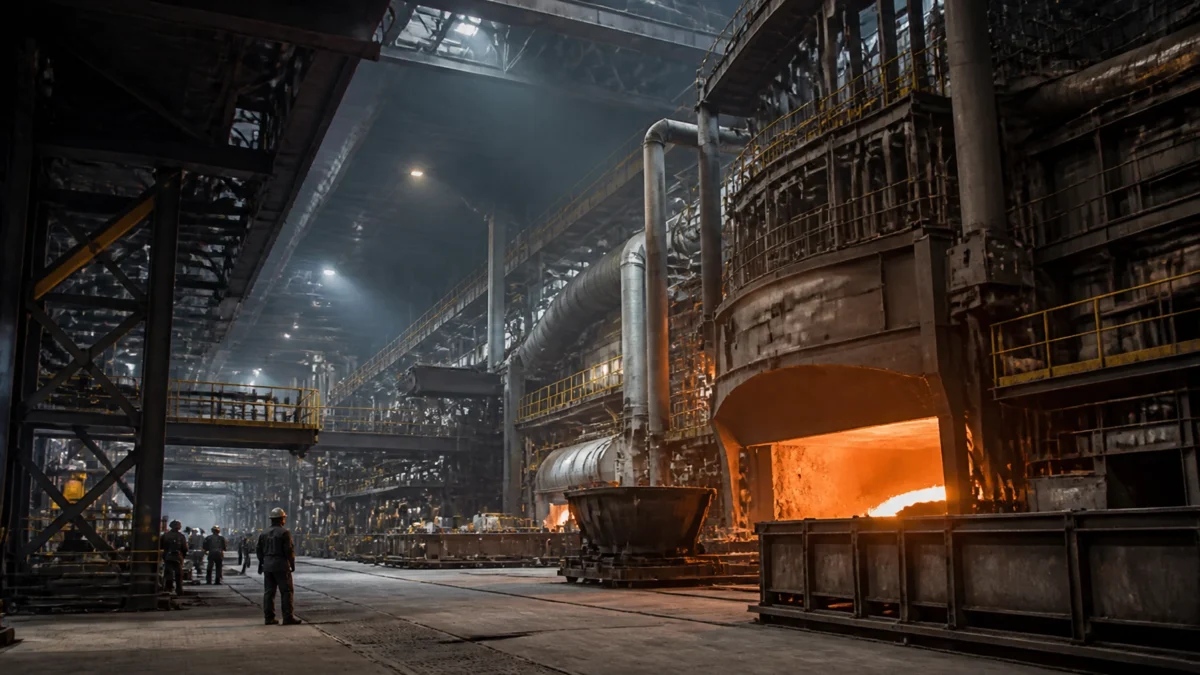
DOE announced the Middletown Works award on August 21. The agency said the $500 million federal investment will support a $1 billion project at Cleveland-Cliffs’ facility and help protect approximately 2,300 jobs.
Cleveland-Cliffs described the agreement as a framework for finalizing negotiations and implementation plans for the previously awarded federal grant. Funding would be divided equally between DOE and Cleveland-Cliffs.
The project will:
- Rebuild and upgrade the plant’s main coal-fired blast furnace
- Deploy artificial intelligence to improve furnace operations and energy efficiency
- Build an on-site cogeneration facility using blast-furnace gas to produce steam and electricity
- Upgrade material-handling infrastructure
- Convert certain industrial byproducts into materials for regional concrete production
Cleveland-Cliffs said the investment would be deployed over four years while the plant continues producing steel. The company expects the blast-furnace rebuild to be completed during the first quarter of 2030.
The project’s scope changed from the original proposal. According to DOE, Cleveland-Cliffs concluded that the business case for the initial plan no longer worked because customers were unwilling to pay a premium for lower-carbon steel. The company and DOE then developed an alternative focused on extending the existing blast-furnace route while improving efficiency and using process gases for on-site energy production.
| Middletown Works project data | Figure |
|---|---|
| DOE award | $500 million |
| Total project investment | $1 billion |
| Cleveland-Cliffs contribution | $500 million |
| Existing jobs the project is intended to protect | Approximately 2,300 |
| Construction start | Expected in the coming weeks |
| Core production asset | Coal-fired blast furnace |
The award therefore does not support a greenfield steel plant. It is an industrial-life-extension and modernization project designed to preserve a facility that produces approximately 3 million tons of raw steel annually for automotive, HVAC, appliance and steel-distribution customers.
The Policy Debate Centers on Emissions and Industrial Resilience
The revised project has drawn competing responses.
DOE and Cleveland-Cliffs have emphasized domestic steel supply, manufacturing employment, energy efficiency and national security. Their position is that preserving production capacity for automotive-grade steel is strategically important, particularly when manufacturers remain exposed to global supply-chain disruptions and foreign competition.
Environmental advocates and some local residents have raised a different concern. Canary Media reported that the original project was designed to replace the existing blast furnace with a hydrogen-ready direct-reduced-iron plant and two electric melting furnaces. Critics argue that redirecting the award toward the existing coal-based blast-furnace route will produce fewer emissions reductions and extend the operating life of higher-emitting equipment.
Those positions reflect a broader policy trade-off. Middletown Works uses an integrated steelmaking route designed to produce automotive-exposed steel grades. The original direct-reduced-iron and electric-melting proposal was also intended to preserve automotive-grade production while lowering emissions, but Cleveland-Cliffs determined that the revised project offered a more viable commercial pathway under current market conditions.
The Middletown decision does not settle the technical and commercial debate over competing steelmaking systems. It demonstrates how federal industrial policy is being applied under present market conditions. The administration and the company prioritized existing production capacity, employment, operational reliability and project economics over the emissions reductions associated with the original proposal.
DOE Is Applying Industrial Support Across Multiple Sectors
The steel announcement followed another $500 million DOE package for seven critical-mineral processing, battery manufacturing and recycling projects.
DOE said the August 20 selections are intended to expand domestic capacity and reduce reliance on foreign sources for materials supporting manufacturing, energy production and national security.
The two DOE announcements show a common structure: federal funding is being used to attract or preserve private investment in sectors considered strategically important.
Federal industrial support announced or authorized recently
| Sector | Federal action | Amount | Current status |
|---|---|---|---|
| Steelmaking | DOE support for Cleveland-Cliffs’ Middletown Works modernization | $500 million federal share of a $1 billion project | Project-specific award framework and implementation planning |
| Critical minerals and batteries | DOE support for seven processing, manufacturing and recycling projects | $500 million combined | Selected projects remain subject to technical, financial and administrative requirements |
| Natural gas and LNG infrastructure | Presidential determination authorizing purchases, purchase commitments and financial instruments under the Defense Production Act | No project-specific amount announced | Federal authority established, but the memorandum itself does not award financing to a named LNG project |
The comparison has an important limitation. The steel and critical-minerals figures are announced awards. The LNG action is primarily an authorization to use federal purchasing commitments and financial instruments. It does not represent a comparable, project-specific $500 million grant.
LNG Policy Has Expanded, but Project Finance Still Depends on Private Markets
The White House has treated LNG and natural-gas infrastructure as part of a broader energy and national-security strategy.
In an April 20 presidential determination, President Donald Trump found that natural-gas transmission, processing, storage, LNG liquefaction, marine loading, export facilities and related distribution infrastructure are industrial resources or critical technology items considered essential to national defense.
The determination identified four barriers to timely development:
- Financing constraints
- Long-lead equipment and construction schedules
- Permitting delays
- Infrastructure bottlenecks
It authorized DOE to make purchases, enter purchase commitments and use financial instruments under Section 303 of the Defense Production Act to support expanded natural-gas and LNG capacity.
The memorandum establishes federal authority to use those mechanisms. It does not identify a particular LNG developer, specify an award amount or guarantee that any project will receive financing.
Energy Intelligence reported on August 21 that developers viewed federal assistance as insufficient at that stage. The central issue is that federal support does not replace the commercial requirements needed for a project to reach a final investment decision.
Most large LNG projects need substantial long-term offtake agreements with utilities, traders or industrial buyers. Those contracts help establish expected revenue and support project financing. A federal purchase commitment, loan or guarantee could strengthen a financing package, but it cannot automatically ensure that commercial buyers will commit to purchasing a project’s output for decades.
Permitting remains another constraint. The White House determination identifies permitting delays as a problem, but authorizing financial support does not automatically resolve environmental reviews, agency coordination, litigation risk, pipeline approvals or state-level requirements. ENMG previously examined these financing, permitting and construction pressures in its coverage of challenges facing U.S. LNG projects.
LNG Demand Exists, but New Capacity Still Carries Risk
The United States is already the world’s largest LNG exporter. In October 2025, the Energy Information Administration reported that U.S. liquefaction capacity stood at approximately 15.4 billion cubic feet per day. EIA projected that North American LNG export capacity could rise from 11.4 Bcf/d at the beginning of 2024 to 28.7 Bcf/d by 2029 if projects under construction enter service as planned.
EIA identified five additional U.S. LNG projects that had reached final investment decision and were under construction at the time of its analysis:
- Port Arthur LNG Phase 1
- Rio Grande LNG
- Woodside Louisiana LNG
- Golden Pass LNG
- CP2 Phase 1
That construction pipeline supports the administration’s position that LNG can strengthen international energy security and create additional demand for U.S. natural gas. ENMG’s analysis of U.S. LNG export growth provides additional context on the country’s expanding role in global gas markets.
The expanding project pipeline also creates risk. New projects must compete for buyers, pipeline capacity, construction labor, specialized equipment and financing in a market expected to have substantially more export capacity.
A more recent development could affect that commercial outlook. On September 18, Reuters reported that the United States and China were discussing reducing or eliminating China’s tariff on U.S. LNG. The negotiations had not been finalized at the time of the report.
Reuters also reported that approximately 24.5 million metric tons of U.S. LNG capacity under construction remained uncontracted to long-term buyers. Renewed Chinese purchasing could support demand, but tariff negotiations are not equivalent to binding offtake contracts or completed project financing.
For LNG companies, federal involvement may be most valuable when it reduces a specific, measurable risk. A purchase commitment could help establish demand. A loan guarantee could improve debt terms. Permitting legislation or regulatory coordination could reduce schedule uncertainty. An undefined promise of assistance is less useful than a mechanism that lenders and buyers can incorporate into project models.

What the Policy Means for the Broader Energy System
The steel and LNG developments are connected through the infrastructure required to build and operate the energy system.
Steel supports pipelines, LNG terminals, power plants, transmission equipment, manufacturing facilities, vehicles and industrial machinery. LNG projects, in turn, require large quantities of steel, compressors, turbines, electrical equipment and construction services. Critical minerals support batteries, grid equipment, electric vehicles, industrial controls and advanced energy technologies.
Federal support in one sector can therefore affect costs and schedules in another. More domestic steel production could reduce exposure to imported materials, although the effect will depend on pricing, product availability and the competitiveness of U.S. mills. Expanded LNG exports could increase demand for natural gas and pipeline infrastructure while also affecting domestic gas markets and regional transportation systems.
Potential beneficiaries include steelworkers, project contractors, domestic manufacturers, mineral processors, qualifying LNG developers and international buyers seeking diversified gas supplies.
Potentially affected groups include competitors that do not receive federal assistance, communities near industrial facilities, consumers exposed to changes in natural-gas markets and taxpayers if supported projects fail to deliver their expected economic or strategic benefits. Environmental outcomes will depend on project design, operating performance, emissions controls and the energy used by each facility.
What to Watch Next
Several indicators will show whether the federal strategy is moving from policy announcements to measurable project results:
- Whether Cleveland-Cliffs finalizes the remaining implementation steps and deploys the investment on schedule
- Whether the Middletown Works blast-furnace rebuild is completed by the first quarter of 2030
- How DOE measures job retention, energy efficiency, emissions and operational performance at the steel facility
- Whether the seven critical-mineral projects reach construction and commercial operation
- Whether DOE identifies specific LNG projects for purchase commitments, loans, guarantees or other financial instruments
- Whether Congress or federal agencies establish more predictable LNG permitting and export-authorization procedures
- Whether LNG developers secure sufficient long-term offtake commitments to reach final investment decisions
- Whether U.S.-China negotiations produce a durable change in LNG tariffs or purchasing
- How additional LNG capacity affects natural-gas prices, pipeline demand and global competition
The immediate lesson is that federal support can advance a project when government and private capital are aligned around a defined investment plan. The LNG experience shows the other side of the equation. Financing tools may reduce individual risks, but developers still require predictable rules, credible buyers and infrastructure that can be delivered on schedule.
The emerging industrial policy is broader than a debate over fossil fuels or lower-carbon technologies. It is an effort to influence the domestic supply chains behind steel, LNG, minerals, nuclear power, electricity and manufacturing. Its results will depend not only on how much federal money is committed, but also on whether supported projects deliver durable economic value without transferring unresolved costs to workers, consumers, communities or taxpayers.
Keep In Touch with Shale Magazine
As the new era of energy unfolds, you can bet we’ll be the boots on the ground to keep you informed. Subscribe to Shale Magazine for sharp insight into the arenas that matter most to your life. And don’t forget to listen to our riveting podcast, The Energy Mixx Radio Show, where our very own Kym Bolado interviews the most extraordinary thought leaders, business innovators, and industry experts of our time.